If you choose a CFD broker because it advertises the tightest spread, you may be optimizing the easiest number to market—not the cost of trading. In many cases, the broker with a fractionally wider quoted spread can leave you with better net results.
That sounds backwards because spread comparison tables have trained traders to think of broker selection as a price-shopping exercise. It is not. For active traders, execution quality matters more than the best-looking number at the moment you open a position.
What everyone believes
The conventional advice is simple: compare brokers, find the lowest spread, and choose the cheapest provider. A broker quoting 0.6 pips on a major forex pair appears better than one quoting 0.8 pips. A broker offering zero-commission trading or ultra-tight spreads looks even more attractive.
Comparison content reinforces this view because spreads are easy to display in a table. They are concrete, familiar, and apparently objective. You can sort providers from lowest to highest and call the result a ranking.
And to be fair, spread matters. If every other condition were identical, paying less to enter a trade would be preferable. A trader who ignores transaction costs entirely is not being disciplined.
But the conditions are never identical. The advertised spread is only one moment in the trading experience—and often not the moment that determines whether the trade works.
Why that’s wrong
The problem is that a headline spread measures the visible price gap at entry. It does not tell you what happens when the market moves quickly, liquidity thins, or you urgently need to get out.
That is where the supposedly cheaper broker can become expensive.
Consider a trader who opens a position when the quoted spread is exceptionally tight. The order is accepted, but the execution price differs from the quote. Or the market moves during the request and the broker requotes. Or the position appears manageable until volatility expands and the trader tries to close it. The exit suffers slippage, turning a small theoretical saving at entry into a much larger realized cost.
The arithmetic is not complicated. Saving a fraction of a pip on entry is useful only if the order is filled at a comparable price and the position can be closed efficiently. A poor exit can erase many small entry savings in one transaction. For an active trader who enters and exits frequently, those episodes matter far more than the spread shown in a calm-market comparison table.
This is particularly important around economic releases, market opens, sudden geopolitical news, and other moments when prices move faster than most retail platforms can display them. A broker can advertise an attractive minimum spread during favorable conditions while delivering a very different trading experience when execution actually matters.
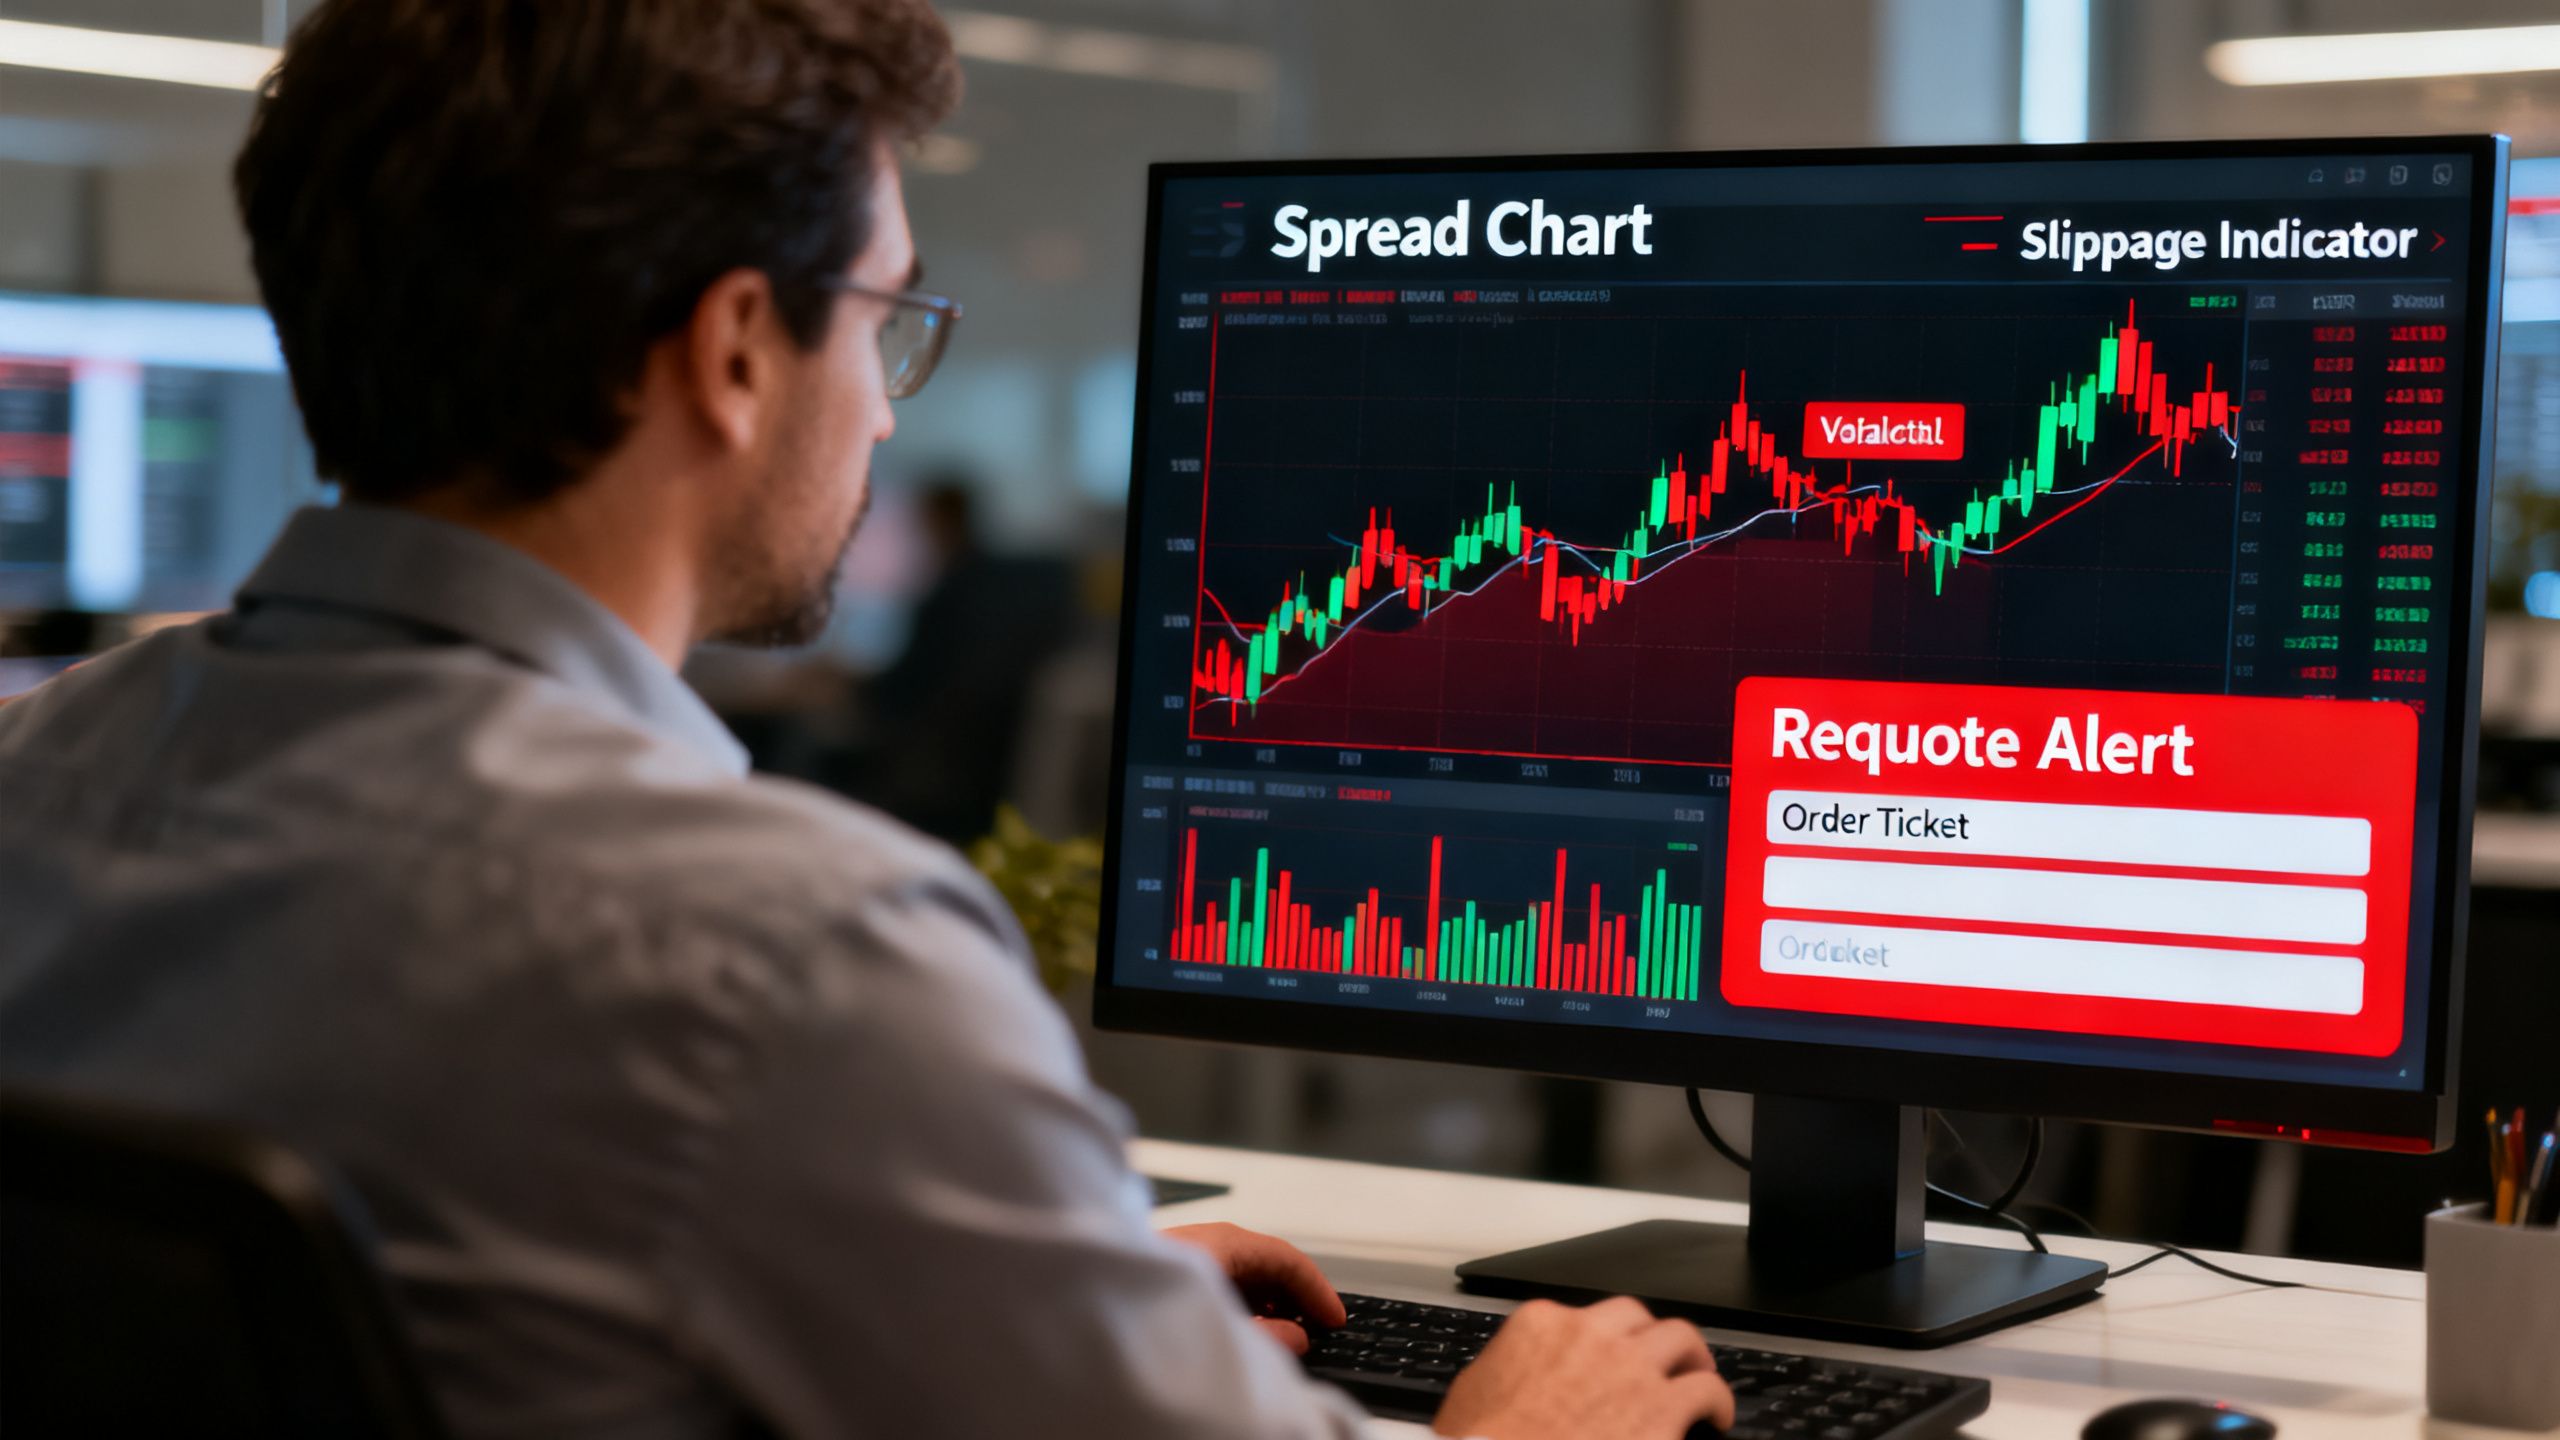
The strongest objection is obvious: a wider spread is a guaranteed cost, while slippage and requotes are occasional. Why not take the guaranteed discount and accept the occasional inconvenience?
Because “occasional” is doing too much work in that argument. Active traders do not experience the market as a sequence of isolated, calm entries. They place repeated orders across changing conditions. A small execution disadvantage that appears only during volatility can be more consequential than a consistently modest spread difference. And the trader often discovers the real cost only after the trade has gone against them.
The right question is not, “What is the broker’s best spread?” It is, “What does this broker typically deliver when I need to trade?”
What I’ve seen instead
The pattern is familiar: traders obsess over the first number they can compare and underinvestigate the parts of execution they cannot summarize in a neat column.
They will spend an afternoon finding a broker that is 0.1 or 0.2 pips cheaper on a major pair. Then they will accept vague answers about execution during news, assume a requote is just bad luck, or fail to record the difference between the expected and actual fill price.
That is backwards.
A broker’s real cost shows up across the entire trade lifecycle. It appears in the price you receive, the speed of confirmation, the frequency of rejected or requoted orders, the slippage on stops and market exits, and the behavior of spreads when volatility increases. These details are less convenient to compare, but they are much closer to the outcome that matters: net returns after trading costs.
The same principle applies beyond forex. On indices, commodities, shares, and cryptocurrencies, the advertised trading condition may look attractive until liquidity changes. A platform that feels efficient in a quiet session may become frustrating when order flow accelerates. A trader using stops or short holding periods is especially exposed because there is less time for a poor fill to be absorbed by the trade thesis.
This is not an argument that every broker with tight spreads is unreliable. Nor is it an excuse for brokers to charge unnecessarily wide spreads. It is an argument against treating one marketing statistic as a complete assessment of execution.
A broker with a slightly wider ordinary spread but consistent fills, fewer requotes, transparent pricing, and reasonable behavior during volatile periods may be cheaper in practice than the broker winning the comparison table.
That is the part the rankings usually fail to capture.
What this means for you
Stop choosing a CFD broker from the spread column alone. Treat the advertised spread as a starting point, not a verdict.
Before committing meaningful capital, test the provider with a small account and record the results. Compare the quoted price with the actual fill. Track slippage on both entries and exits. Note whether orders are requoted, rejected, or delayed. Test the platform in normal conditions and, where appropriate, observe how it behaves around scheduled volatility.
Pay particular attention to exits. Traders often focus on the cost of opening a position because that is where brokers advertise their advantage. But the cost of closing is where execution quality can directly affect a realized gain or loss. A broker that looks cheap at entry but routinely produces poor fills when you need out is not cheap.
Also match the broker to your strategy. A position trader who holds for weeks may care less about a fraction of a pip than a scalper placing dozens of trades. A trader who relies on stop orders should investigate how those orders have historically been handled in fast markets. There is no universal “best broker” separate from the way you trade.
Ask better questions:
- Are spreads fixed, variable, or simply advertised at their best?
- How often do requotes or rejected orders occur?
- What happens to spreads during major market events?
- How much slippage should you expect on market orders and stops?
- Can you review execution reports and compare requested versus filled prices?
- Is the platform reliable when trading activity surges?
You will not eliminate execution risk. No broker can control every market movement. But you can stop confusing an attractive quote with a low total cost.
The bottom line
The broker with the lowest advertised CFD spread is not automatically the broker that costs you the least. If execution is poor during the moments that matter, a slightly wider spread can be the cheaper choice.
Choose the provider that delivers reliable execution—not the one that wins the simplest comparison table. Measure what happens to your orders in real trading conditions, especially when you need to exit. That is the way to make a broker decision based on net results rather than marketing optics.